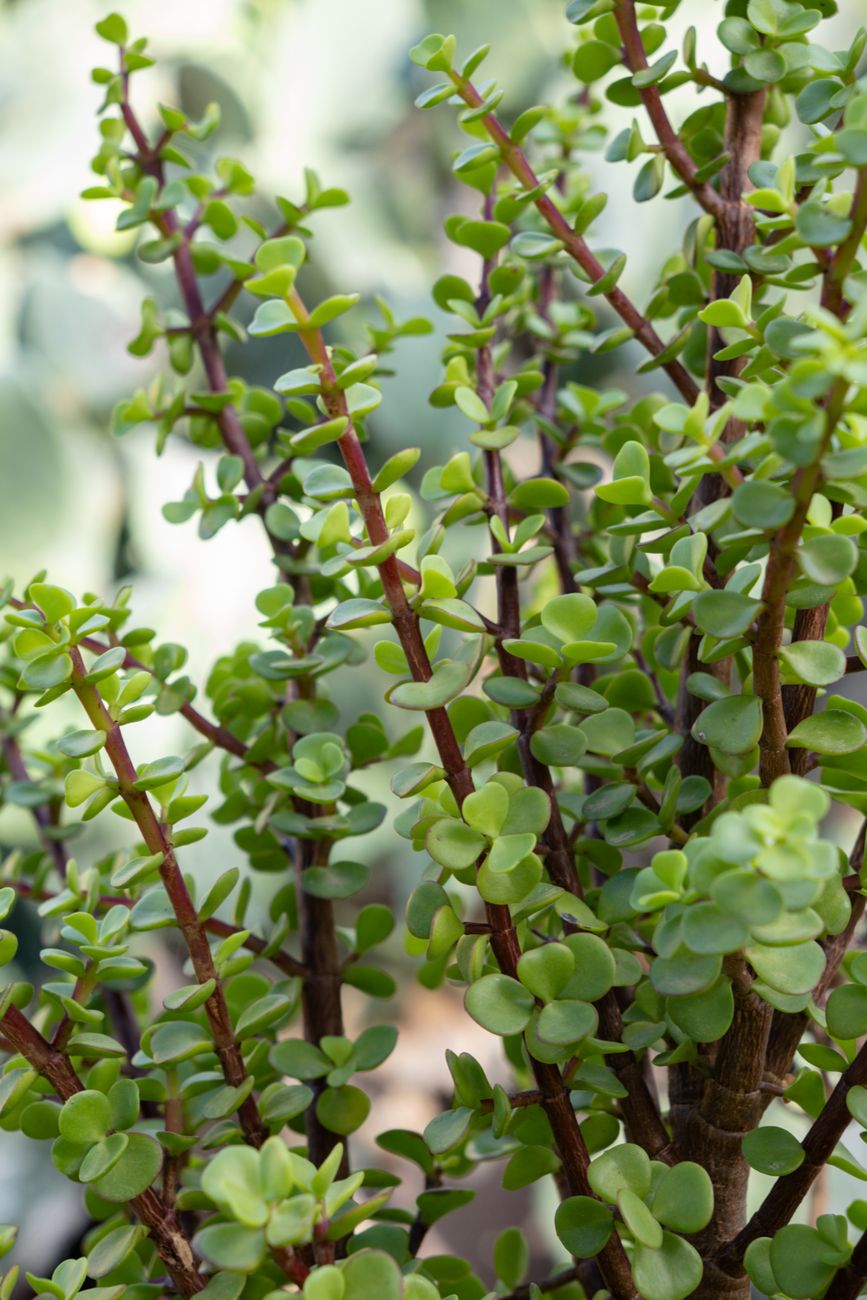
It’s been 15 years since I stood in South Africa’s Eastern Cape thicket learning about the impressive carbon sequestration capacity of Spekboom, a drought-resistant succulent indigenous to the area.
Studying Environmental Science at Grahamstown’s Rhodes University, there was a lot of hype around it. I even told farming friends from the Eastern Cape to consider growing it on their farms. Over time I’d heard drips and drabs of projects here and there, but nothing lived up to the initial hype.
Fast-forward 15 years, and I almost spat the first sip of my morning coffee on my laptop when I came across news that Amazon, the subject of much of my ‘boycott big corps’ talk, had committed to purchasing 1.95 million tons of carbon removal credits from a spekboom restoration project.
After a bit more digging, I was further delighted to discover that Amazon’s long-term commitment gave the World Bank enough revenue certainty to price a $120 million Spekboom Restoration Outcome Bond, structured to mobilize $25 million of private capital to further support the project.
It got me thinking about how many other such nature-based bonds are out there, and their effectiveness in raising capital to support such big nature-based carbon removal and restoration projects.
What is the spekboom restoration project?
The spekboom project aims to plant around 150–180 million cuttings on 50,000 hectares of degraded farm land in the Eastern Cape’s Albany thicket biome, with roughly 35 million tonnes of CO2e expected to be removed over a 40-year period.
Spekboom competes with other best-in-class solutions in the natural carbon removal space because it achieves carbon sequestration rates of approximately 15–29 tCO2e/ha/year, comparable to a tropical rainforest per hectare, but while thriving in a hot, dry subtropical landscape.
Spekboom restoration, a methodology recognized by the United Nations as a World Restoration Flagship for its outstanding contributions to restoring nature and delivering critical benefits to communities, also improves soil quality, water retention, and climate resilience, while fostering microclimate and soil conditions needed to revitalize the biodiverse ecosystem that support other plant and animal species.
The project is expected to create 11,000 local jobs, including through small and medium-sized enterprises that will deliver spekboom harvesting, planting, monitoring, and ongoing land management. That’s massive, given the shocking 40%+ average unemployment rate in the area.
A look at the mechanics of the bond itself
By committing to purchase 1.95 million tons of carbon removal credits generated over more than a decade, Amazon functions as the “forward purchase agreement”, locking in future demand before the plants have grown enough to issue a single credit.
That long-term commitment gave the World Bank the confidence to price the bond, its longest-dated outcome bond to date, maturing in 2040. Bondholders take a lower fixed coupon than they would on a regular World Bank bond; the value of that foregone coupon is redirected, via a hedge arrangement with BNP Paribas, as upfront project financing. In return, investors get a variable bonus return tied to how many carbon credits the project actually delivers.
Alongside the bond, a group of institutional investors like Mirova (a Paris-based asset manager), Bregal Sphere (a London-based investor), Singapore’s GenZero, and US-based Rubicon Carbon put in a further $66 million.
This came on the back of independent rater BeZero Carbon giving the project an “AA” pre-issuance rating, signalling high confidence the planned credits will represent genuine verified removal once issued.
Credits from this project meet Amazon’s rigorous quality bar. They are verified under Verra’s ABACUS label, which uses a treatment- control methodology to measure additionality and requires projects to maintain agricultural productivity in surrounding areas.
Certification under Verra’s Climate, Community and Biodiversity (CCB) Standard further validates the project’s social and biodiversity co-benefits.
So how does this compare with other outcome, or Environmental Impact, bonds?
The Rhino Bond
The Rhino bond is a $150 million, five-year bond structured to protect two South African reserves and grow the black rhino population by at least 4% a year following a poaching crisis which has brought their numbers down by a shocking 94.4%.
The bond was designed to fund conservation activity in two protected areas in Addo Elephant National Park (managed by South African National Parks) and Great Fish River Nature Reserve (managed by Eastern Cape Parks and Tourism Agency) — the same province, coincidentally, where the Spekboom project now sits.
The bond was priced by the IBRD (International Bank for Reconstruction and Development) as a Sustainable Development Bond where investors received no interest payments at all during the bond’s life. Odd for a AAA-rated instrument, sure. Instead, at maturity, investors got their principal back plus a “conservation success payment”, up to $13.76 million, calculated on a sliding scale tied to the actual black rhino population growth rate achieved. The growth rate was independently calculated by Conservation Alpha and verified by the Zoological Society of London, playing the same role BeZero Carbon plays for Spekboom.
Regarding structuring of the deal, this was done by Credit Suisse, with other early supporters including the Oak Foundation, the Rufford Foundation, and the UK government’s Illegal Wildlife Trade Challenge Fund.
The Seychelles’ sovereign blue bond
The Seychelles’ sovereign blue bond is a $15 million bond structured to protect 30% of the Seychelles’ ocean territory and shore up an economy where fisheries are second only to tourism.
The bond was built directly on a 2015 debt-for-nature swap Seychelles had done with The Nature Conservancy in exchange for greater ocean protection, and fed into the World Bank’s regional SWIOFish3 program that supports sustainable fisheries governance across the South West Indian Ocean.
By guaranteeing $5 million of 15, the World Bank made the loan look safer to lenders, enough to cut 2 percentage points off the interest rate. Add to this the Global Environment Facility (GEF) chipping in another $5 million, but as a top-up specifically to help cover the interest payments, and the Seychelles ends up paying only approximately 2.8% interest instead of 5.5%.
What’s interesting is that this was one of the first times anyone had stacked a guarantee plus a subsidy like this specifically to make an environmental project cheap enough for a small country, like the Seychelles, to finance.
Are these bonds actually effective?
The Rhino Bond’s underlying population did grow enough to trigger investor payments. The Seychelles model has been replicated six times as The Nature Conservancy’s “Nature Bonds Program” (Belize 2021, Barbados 2022, Gabon 2023, The Bahamas 2024, Ecuador 2024), each swapping expensive government debt for cheaper, conservation-linked debt.
However, according to many the numbers don’t come close to matching the problem. Critics also point to structural design flaws: some nature-linked bonds raise a country’s interest rate if it misses its target, which can end up punishing a country for a drought or wildfire, rather than genuine mismanagement.
Also, these bonds mature in 5–14 years, but ecosystem recovery operates on decadal-to-generational timescales. This begs the question, what happens to the rhinos or the reef after the bond matures and investor attention moves on?
 Leading SME ESG reporting platforms

Leave a comment